Competitive Price, Trusted Advice

Arborist Insurance in Texas

Experience easy access to affordable, high-quality Arborist Insurance at David King Insurance.

Proudly Serving Texas, Oklahoma, Arkansas, New Mexico, Colorado, Connecticut, Michigan, Alabama, Iowa, Washington, Montana, Arizona, South Carolina, Kansas & Missouri.

Get your Arborist Insurance quote below!

David King Insurance | Insurance in Texas

Tree care professionals face a variety of risks, from falling branches and damaged property to equipment accidents and employee injuries. Whether you specialize in pruning, tree removal, or storm cleanup, unexpected incidents can disrupt operations and create significant expenses. Arborist Insurance can help your business prepare for certain covered losses and manage the financial risks associated with tree care.

David King Insurance helps Texas business owners explore insurance options suited to their operations. Whether you run a small tree trimming company or manage a crew handling large-scale removals, Texas Tree Service Insurance can be tailored to your services, equipment, and workforce. The right combination of policies can help you address common exposures while keeping your business prepared for changing demands.
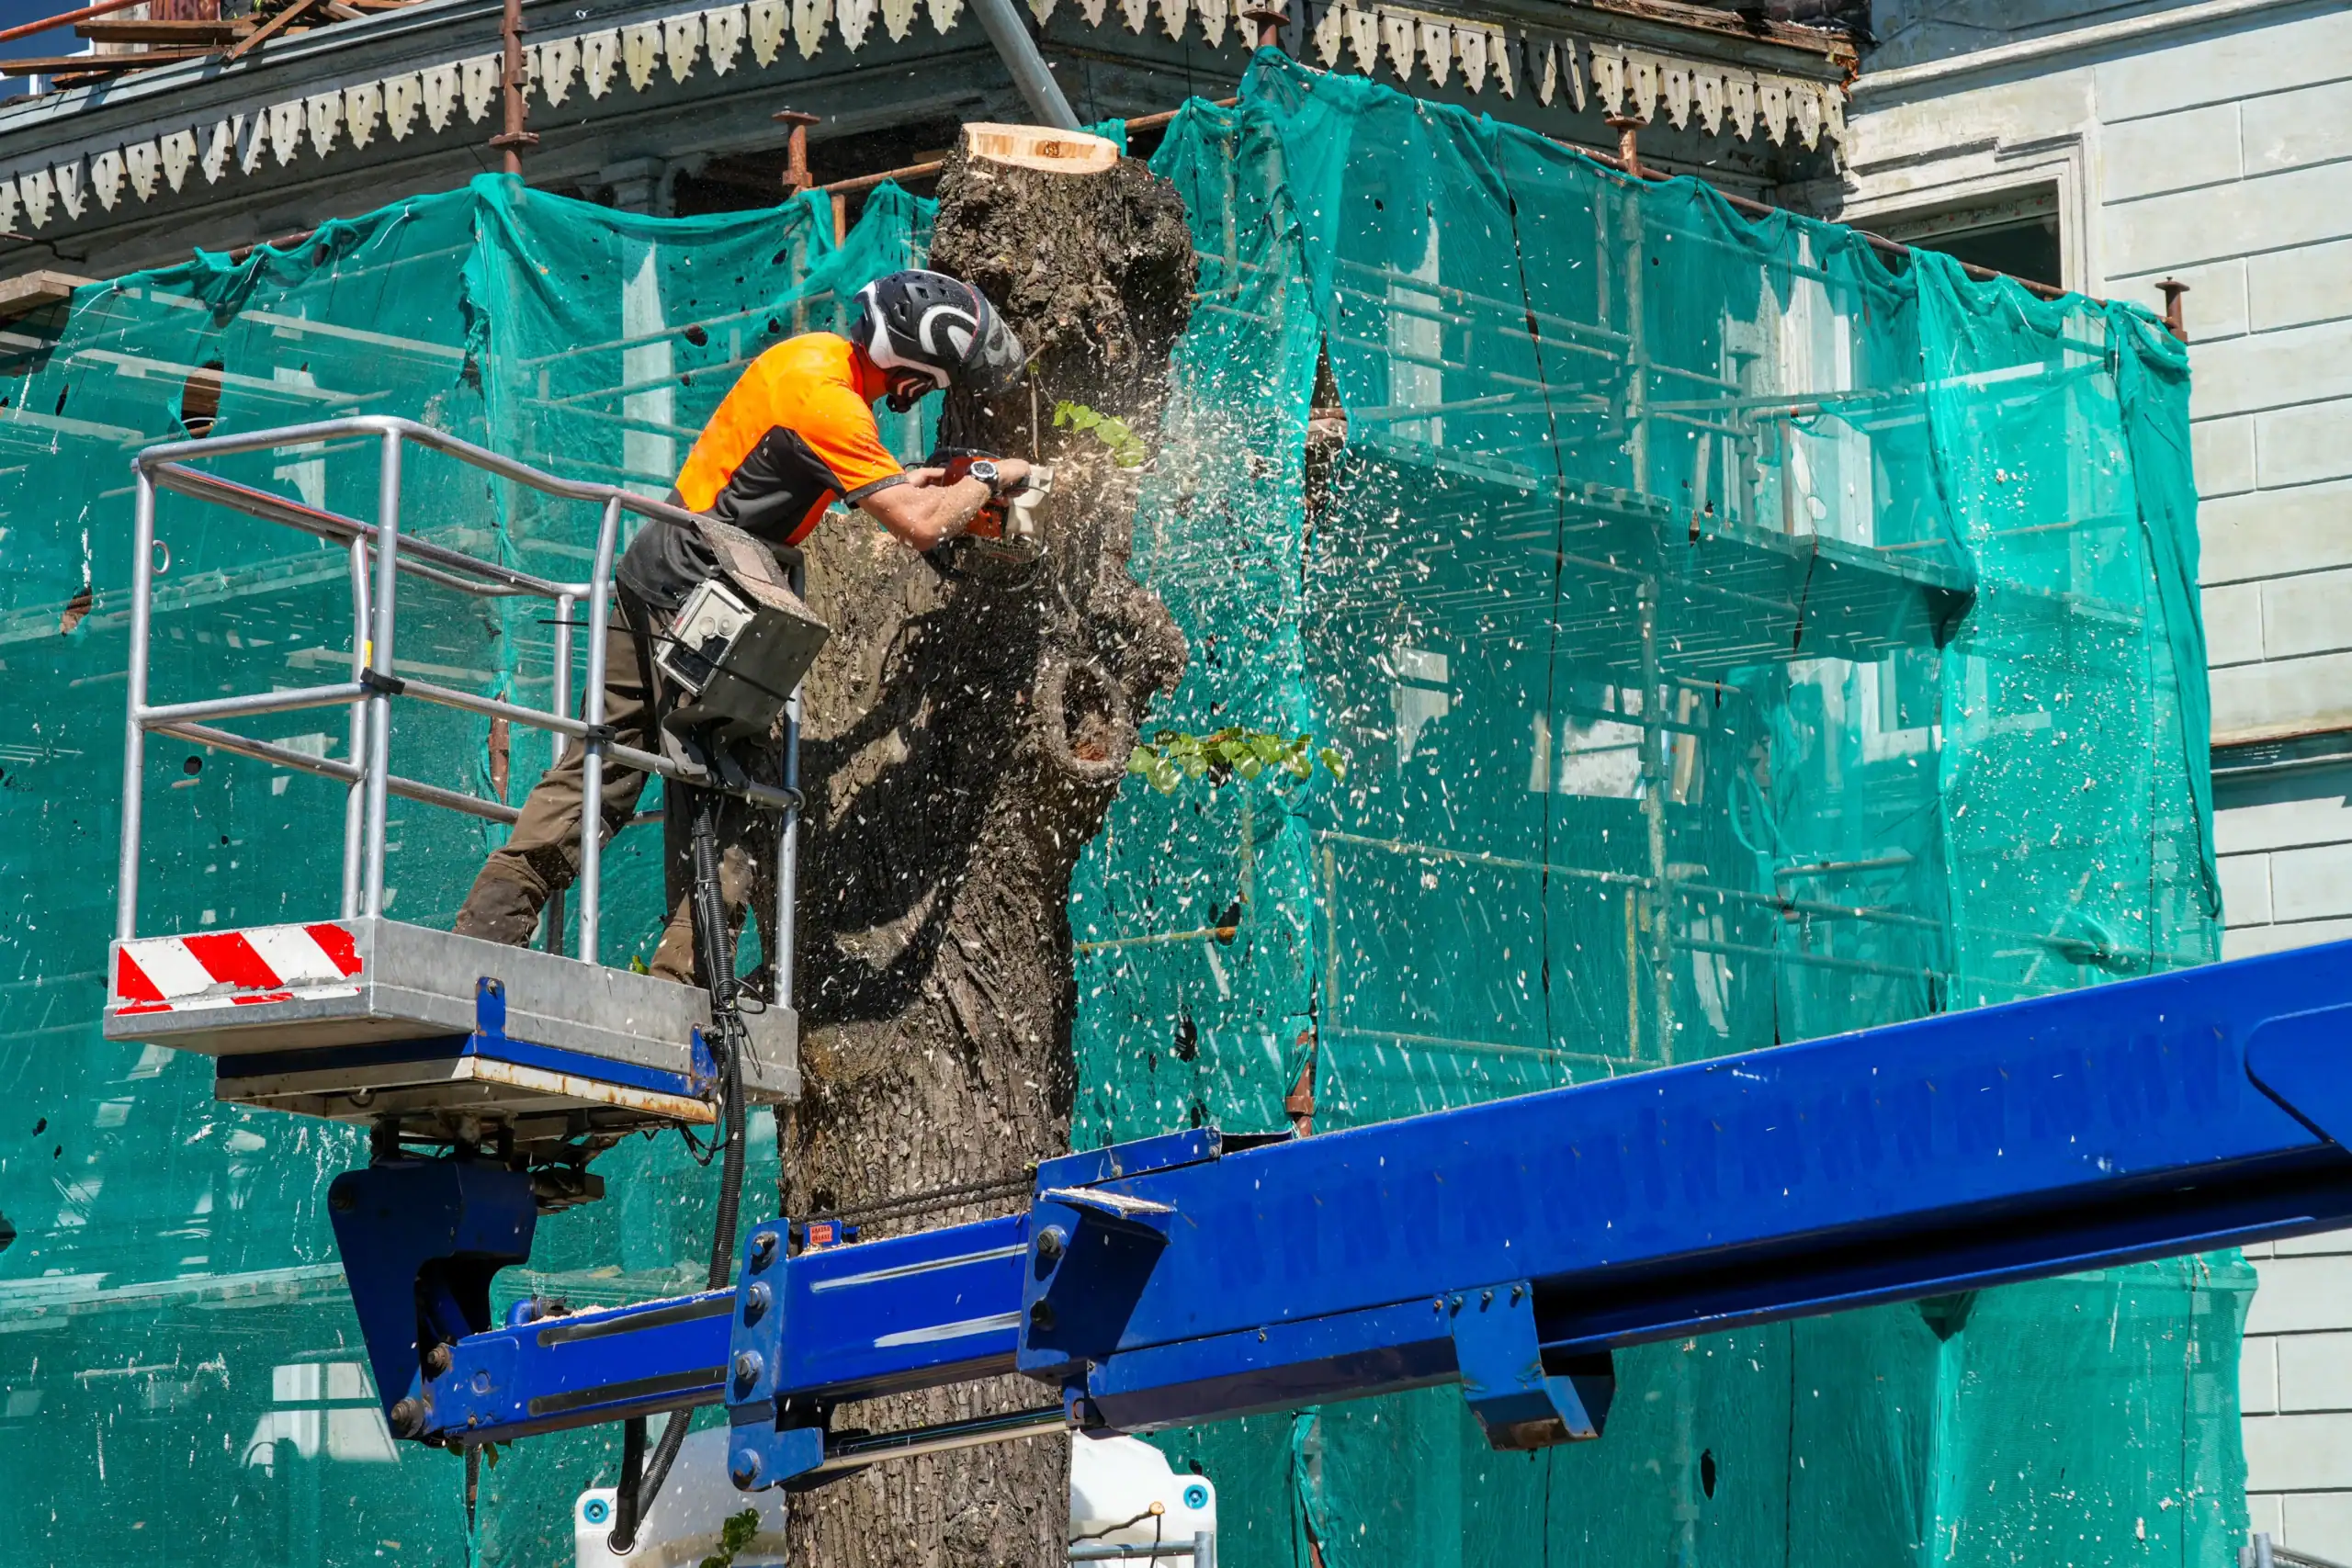
Arborist performing tree trimming on a lift with safety gear.

What Is Arborist Insurance in Texas?

Arborist Insurance combines coverage options designed for professionals who prune, maintain, plant, and remove trees. Depending on your operations, a policy package may include general liability, commercial auto, workers’ compensation, and equipment coverage.

Tree care often involves chainsaws, wood chippers, climbing gear, and bucket trucks. An accidental falling limb could damage a customer’s home, while a vehicle accident could affect your ability to reach scheduled jobs. Appropriate insurance may help address certain financial consequences of covered incidents.

At David King Insurance, we can help you explore options based on your services, crew size, equipment, and contracts. A business focused on routine pruning may have different needs from one specializing in hazardous tree removal. Reviewing these differences can help you identify suitable coverage for your operations.

Get a quote for Arborist Insurance

Why Do Tree Service Businesses in Texas Need Insurance?

Tree service work presents risks that can lead to costly property damage, injuries, and legal disputes. Branches may fall unexpectedly, machinery can malfunction, and ground conditions can change during a project. Insurance can help manage certain covered losses and reduce the financial burden of eligible claims.

For example, a tree removal project near a home could result in damage to a roof, fence, or neighboring structure. If a customer alleges that your work caused the damage, general liability insurance may help with covered claims and legal expenses, subject to policy terms.

Insurance may also be important when working with commercial property managers and contractors. These clients sometimes require proof of insurance before approving work. Maintaining appropriate coverage and documentation can help your business meet contractual requirements and demonstrate responsible risk management.
  • Your insurance needs depend on the services you provide, the equipment you use, and the risks your business faces. David King Insurance can help you review options that may include:

    • General Liability Insurance: May address covered third-party bodily injury, property damage, and certain personal or advertising injury claims.
    • Workers’ Compensation Insurance: May provide benefits for eligible work-related injuries or illnesses, subject to applicable requirements.
    • Commercial Auto Insurance: May cover certain accidents involving insured business vehicles.
    • Tools and Equipment Coverage: May help pay for covered losses involving eligible chainsaws, chippers, and climbing gear.
    • Inland Marine Insurance: May protect eligible movable property in transit or at job sites against covered losses.
    • Commercial Property Insurance: May cover insured business buildings and contents against specified losses.

    Not every business requires every option. Coverage availability, limits, deductibles, and exclusions vary by policy. Reviewing these details with an insurance professional can help you understand how different policies may address your exposures.

  • Tree care employees regularly work at heights, operate powerful machinery, and handle heavy branches and logs. These tasks can expose workers to falls, cuts, and injuries from falling objects. Safety training, equipment maintenance, and clear job-site procedures remain essential, but accidents can still happen.

    Workers’ compensation insurance may provide benefits for eligible work-related injuries and illnesses, including certain medical expenses and wage replacement. Employers should review applicable Texas requirements to understand their responsibilities. Other policies may address separate exposures, such as third-party injury claims or accidents involving company vehicles.

    When evaluating your insurance needs, consider employee duties, crew size, and whether subcontractors perform specialized work. An insurance review can help identify options suited to your workforce and the activities your employees perform each day.

  • Insurance premiums vary according to your business’s size, services, and risk profile. A company performing routine residential pruning may have different underwriting considerations from one removing large trees near buildings or handling emergency storm cleanup.

    Insurers may consider several factors:

    • Services Performed: Tree removal and emergency response may involve different exposures from routine maintenance.
    • Payroll and Staffing: Employee numbers, payroll, and job duties may affect certain premiums.
    • Vehicles and Equipment: The value and use of trucks, trailers, and specialized machinery can influence costs.
    • Claims History: Previous losses may affect underwriting decisions and available terms.
    • Coverage Limits: Higher limits and additional options can increase premiums.

    Your operating territory, safety practices, and contractual obligations may also influence available coverage. Providing accurate business information helps insurers assess your needs. Comparing policy terms, exclusions, and deductibles alongside premiums can help you make an informed decision.

  • Start by identifying the services your company performs, whether tree trimming, stump grinding, hazardous tree removal, or commercial property maintenance. Each activity may introduce different risks that deserve consideration when selecting insurance.

    Next, assess your equipment, vehicles, employee responsibilities, and customer contract requirements. If your crews transport expensive machinery between job sites, ask how available policies address those exposures. Review coverage limits, deductibles, exclusions, and claims conditions so you understand the protection being offered.

    Your needs may change as your company grows. Hiring employees, purchasing vehicles, or expanding into larger projects can affect your insurance requirements. David King Insurance can help you review your operations and explore options appropriate for your business.

Arborist Insurance Texas

How Can You Get Started with Arborist Insurance?

Choosing insurance is an important step in managing a tree care business. David King Insurance can help Texas arborists and tree service contractors explore options based on their equipment, workforce, services, and business goals.

From general liability and commercial auto to workers’ compensation and equipment coverage, a suitable combination of policies may help address common operational risks. Actual protection depends on policy terms, conditions, limits, and exclusions, so reviewing the details is essential.

Contact David King Insurance today to discuss Arborist Insurance and Tree Service Insurance for your Texas business. Our team can help you explore available coverage options and find solutions that align with your operations.

David King Insurance

Headquarters

549 E Sandy Lake Rd Suite 100
Coppell TX 75019
Send us a Message!